Selling as is · November 4, 2026 · 6 min read
Storm damage in Florida: the claim deadlines to know before you sell
Published by BIMINIO Properties, a company that buys houses for cash in Florida and Arizona.
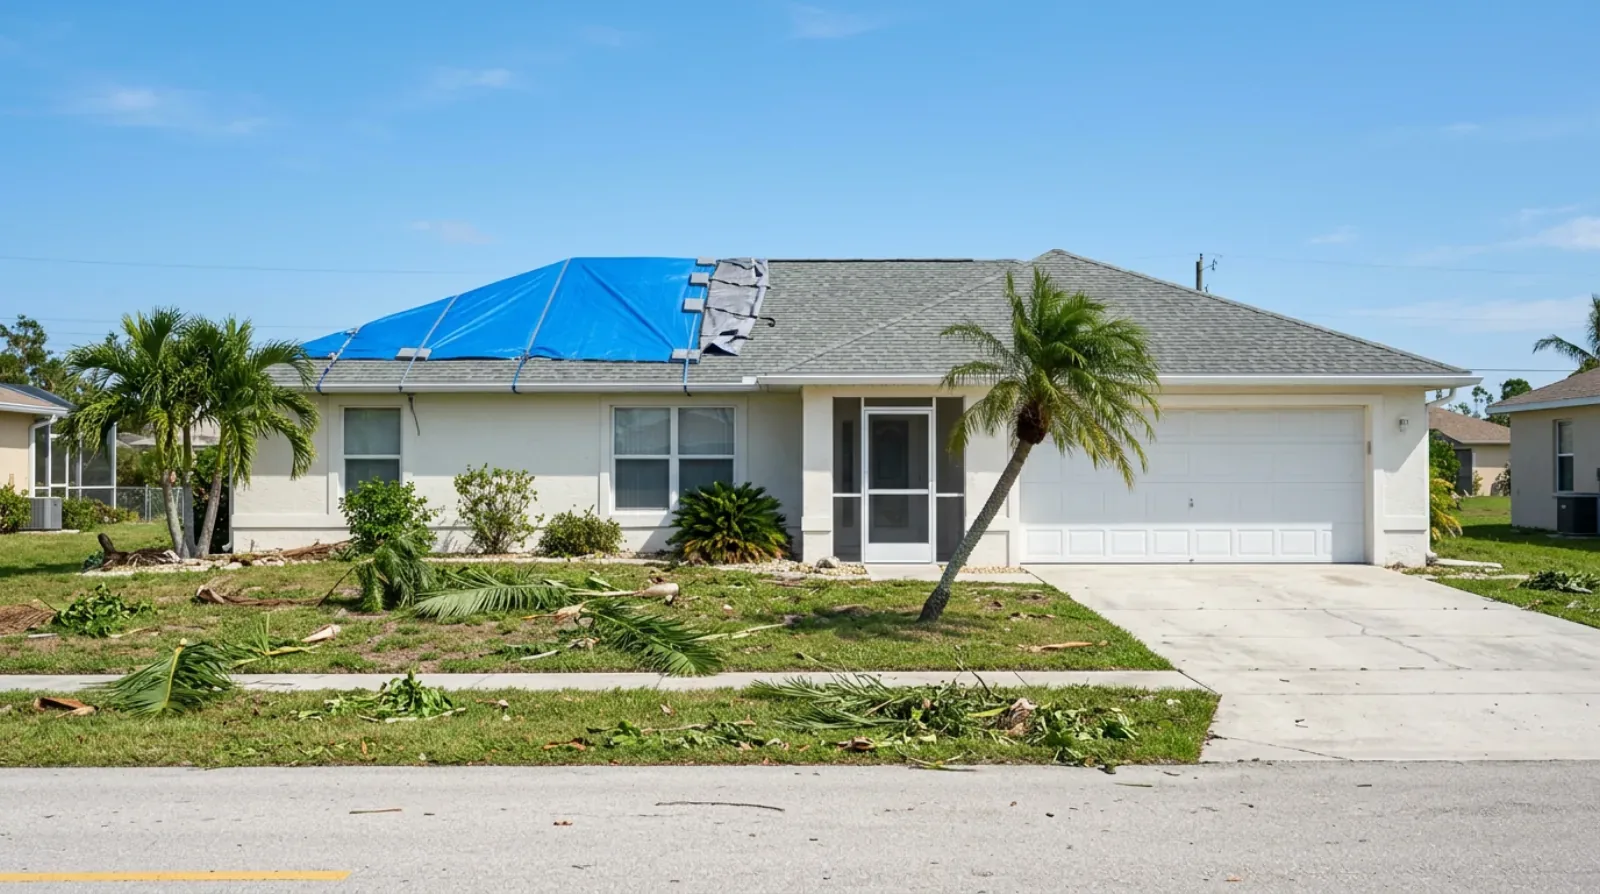
After a storm, a Florida owner can face two choices at once: repair the house, or sell it as it is. Before you decide, know the insurance deadlines. They keep running whether you sell or not.
The deadlines in Florida law
Florida Statutes section 627.70132 sets the time limits for telling your insurer about a property claim:
| Claim | Deadline to give notice |
|---|---|
| New claim | Within 1 year after the date of loss |
| Reopened claim | Within 1 year after the date of loss |
| Supplemental claim | Within 18 months after the date of loss |
A claim is barred if notice is not given within these limits, in the way your policy requires.
For a hurricane, the same section says the date of loss is the date the hurricane made landfall. For a windstorm, it is the date the National Oceanic and Atmospheric Administration verifies the event.
The section also defines the two later kinds of claim:
- A reopened claim is one the insurer closed, then reopened at your request for more costs for damage you already reported.
- A supplemental claim is for more damage from the same event that the insurer already adjusted, or for costs that came up while repairs were underway on an open claim you reported in time.
The time limits pause during a deployment to a combat zone or combat support posting that affects a servicemember's ability to file.
What your insurer must do, and when
Florida Statutes section 627.70131 sets deadlines for the insurer once you report a claim:
| Step | Deadline |
|---|---|
| Acknowledge your claim and send forms and instructions | Within 7 calendar days of your communication |
| Begin its investigation | Within 7 days after it receives your proof of loss |
| Inspect the house in person, if it does so | Within 30 days after it receives your proof of loss |
| Send you a copy of any detailed estimate its adjuster makes | Within 7 days after the estimate is made |
| Pay or deny the claim, or part of it, with a written reason | Within 60 days after it receives notice of the claim |
The adjuster must give you their name and state license number. A payment made after the 60 days carries interest from the date the insurer received notice, under the conditions in the section.
Why this matters when you sell
Damage you have not reported does not disappear when the house changes hands. If you plan to sell, decide about the claim first, so you do not lose it by waiting.
Three things to settle early:
- Report the damage. Give notice to your insurer within the deadline, even if you plan to sell. Take photos before anything is cleaned or moved.
- Ask who gets the claim money after a sale. Your policy, your insurer and your lender all have a say. Ask the insurer in writing, and talk to a lawyer if the amount is large.
- Tell the buyer about the claim. An open, paid or denied claim is part of the house's story. A buyer who knows about it can price it in from the start.
How a replacement cost policy pays
The first insurance check can be smaller than the repair estimate. Florida Statutes section 627.7011(3)(a) explains why. On a dwelling insured for replacement cost, the insurer must first pay at least the actual cash value of the loss, less the deductible. It pays the rest "as work is performed and expenses are incurred." When the house is a total loss, it pays replacement cost without holding back depreciation.
So if you sell before the repairs are done, the part of the claim tied to repair work may still be unpaid. Ask your insurer in writing what has been paid, what remains, and what it needs to release the rest.
Passing the claim to the buyer
Since 2023, Florida law limits who can take over a claim. Section 627.7152(13) says that for residential policies issued on or after January 1, 2023, an owner may not assign post-loss insurance benefits. Subsection (11)(a) makes an exception for an assignment to "a subsequent purchaser of the property" with an insurable interest, following a loss.
That means the buyer of a damaged house can be the one who takes over the claim. Whether that is the best plan depends on how much has been paid, your lender's rights and the contract. Agree on it in writing before closing, and ask a lawyer to review it when the amount is large.
Repair first, or sell as is?
Repairing before you sell can raise the price, but it takes money and time, and the repair work may have to wait for the insurer's decision. Each month of waiting adds mortgage interest, taxes, insurance and the risk of more damage to an empty house.
Selling as is ends those costs sooner. The buyer takes on the repairs. The price is lower than for a repaired house, because the repair cost comes off.
To compare the two paths with your own numbers, use the net proceeds calculator. Our guide on selling as is covers what to tell a buyer.
What we ask about a damaged house
When you call BIMINIO about a house with storm damage, we ask:
- What happened, and on what date.
- Whether you have reported it to your insurer, and where the claim stands.
- What has been repaired or covered so far, such as a tarp on the roof.
- Whether anyone lives in the house.
We buy houses in any condition in Tampa, Miami, Orlando and Lakeland. The repair budget behind your offer comes from a scope of the work led by our founder, a trained architect. You get a written offer within 24 hours, and you pick a closing date from 7 to 35 days out.
Thinking about selling? BIMINIO buys houses in Florida and Arizona as is. A written offer comes within 24 hours, and you pick the closing date.
Sources
- Florida Statutes (2026), section 627.70132: notice of property insurance claim, read November 8, 2026
- Florida Statutes (2026), section 627.70131: insurer's duty to acknowledge and investigate claims, read November 8, 2026
- Florida Statutes (2026), section 627.7011: homeowners' policies, replacement cost, read November 8, 2026
- Florida Statutes (2026), section 627.7152: assignment agreements, read November 8, 2026
Situations this helps with
Guides
- Selling as is: what to tell the buyer
- How a cash offer is worked out
- Work done without a permit, or an open permit
- Repair first or sell as is?
- Selling a house with an old roof
- Selling a fire or water damaged house
- Selling during hurricane season in Florida
- Selling a vacant house
- Selling a storm-damaged house with an open claim
- Selling a building lot or vacant land
This post is general information. BIMINIO does not give legal, tax or financial advice.